
In the months to come there will be many opportunities to short the bond contract.
One of the best opportunities is provided by US Treasury auctions.
We are now in the middle of a $13 billion long bond auction.
Pay close attention to the way bonds trade for the next week or so.
Paterson advised clients to sell bonds at the 117.16 level with a 16 tick stop.
Traders will close out the position on the next major sign of weakness.
* * * * * J B K * * * * *
San Francisco
Tuesday, March 09, 2010


Saturday, February 27, 2010
Market Roundup
Summary
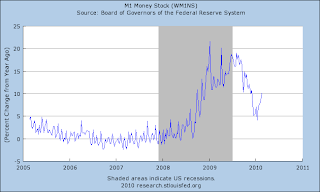
The following three graphs tell the story. M2 and MZM are still slowing. Only M1 is growing, and that is probably due to increases in the Base. Banks are not lending.


The CRB trend has resumed its upward path.

Price deflators are still benign.
Leading Economic Indicators signaled continued growth last week.
Stock Market
Tactics
Money market arbitrage gets harder and harder as spreads collapse and competition increases. To achieve even a 100 basis point spread between liabilities and assets requires taking on credit risk. The money market desk will earn its pay in the coming months.
Strategy
So far, the strategy of shortening asset maturities and lengthening liabilities has worked nicely. Keep doing it.
Tell the board it's time to find some credit worthy borrowers.
Make sure hedging operations are in place. Give the long bond desk a small position and encourage day trading: buying at support and selling at resistance. Get ready for the big short. It's coming.
- Correction in the stock market is over.
- Money supply still not growing
- Inflation begins
- Interest rates not rising
- Bank lending still falling
- GDP soars
- Business cycle growth continues
- Stock market in orderly move higher
- Government stimulus continues
- Dollar mixed
The following three graphs tell the story. M2 and MZM are still slowing. Only M1 is growing, and that is probably due to increases in the Base. Banks are not lending.


Monetary base continues to grow.

Inflation
The first signs of inflation came with the PPI for December with an increase of 1.4% for the month.The CRB trend has resumed its upward path.

GDP Soars
Economic growth continued this past quarter at increased at an annual rate of 5.9 percent in the fourth quarter of 2009 . In the third quarter, real GDP increased 2.2 percent.Price deflators are still benign.
Leading Economic Indicators signaled continued growth last week.
Stock Market
The stock market punched through resistance and made new highs for the move, heading for a resumption of the uptrend.
European investors poured money into US equities again this week, abandoning their own stock markets in favor of American investments.
Money market arbitrage gets harder and harder as spreads collapse and competition increases. To achieve even a 100 basis point spread between liabilities and assets requires taking on credit risk. The money market desk will earn its pay in the coming months.
Strategy
So far, the strategy of shortening asset maturities and lengthening liabilities has worked nicely. Keep doing it.
Tell the board it's time to find some credit worthy borrowers.
Make sure hedging operations are in place. Give the long bond desk a small position and encourage day trading: buying at support and selling at resistance. Get ready for the big short. It's coming.


Tuesday, February 23, 2010

Saturday, February 20, 2010
Time to Sell Bonds
The disaster in the bond market gained a new wreck this week with the release of the PPI.
An increase of 1.4% in one month is a warning to fixed-income investors that the inflation is back, and will build as the economy expands and banks resume lending.
Bonds are at the lows of a recent trading range and are poised to trade lower.
The following events will trigger a sell-off in bonds.
If your institution is selling bonds during one of these events, make sure you're hedged.
* * * * * J B K * * * * *
San Francisco
An increase of 1.4% in one month is a warning to fixed-income investors that the inflation is back, and will build as the economy expands and banks resume lending.
Bonds are at the lows of a recent trading range and are poised to trade lower.
The following events will trigger a sell-off in bonds.
- Money supply increases - M1, M2, MZM
- Price increases - PPI, CPI, CRB
- Quarterly refundings - 10 year notes and 30 year bonds
If your institution is selling bonds during one of these events, make sure you're hedged.
* * * * * J B K * * * * *
San Francisco
Sunday, February 07, 2010
Correction time for stocks
How big will this correction be?

Right now, we are at minor support: 1090 on the S&P 500.
If we drop below this level, the correction will continue for another 60-120 points.
At least.
At most, we could see a return to the lows of last March: somewhere in the 875 range.
This is not entirely implausible.
Recall the bottom back in 2002-3. There we saw a return to the same levels three times.

It could happen again, and for one simple reason.
The Federal Reserve will be selling bonds for the near future at a record clip, not buying them as they did during the last year.
Combined with US Treasury sales, the bond market will be under constant selling pressure for years to come.
Interest rates will rise.
As interest rates rise, the value of stocks must pause until rates settle down.
That is the situation facing us now.
SUMMARY
We are still in a bull market, and the bull market will continue.
But, be careful about adding new positions in the equities area.
Consider shorting this market if it drops below 1090.
Evaluate short positions every three days.
TACTICS
- Money market arbitrage is still the best option for spread bankers.
- Extend the maturity of liabilities
- Find credit worthy borrowers.
- Tell the board that long rates will be rising
- Short rates will not be rising
- Credit spreads will be narrowing
- Consider fee-based income alternatives
Thursday, February 04, 2010
Factory orders rose 1.0 percent in December | Reuters
WASHINGTON (Reuters) - New orders at factories jumped by an unexpectedly large 1 percent in December despite a drop in transportation equipment orders, while inventories shrank, a government report showed on Thursday.
Analysts polled by Reuters expected orders to increase by 0.5 percent. Factory orders for November were revised up to a 1 percent gain.
Transportation orders fell by 0.5 percent on a 34.1 percent drop in civilian aircraft orders. Excluding transportation, new orders rose 1.2 percent in the month.
Inventories fell for the first time in three months, dipping 0.1 percent.
The inventories-to-shipments ratio slipped to 1.29, the lowest since August 2008.
http://www.reuters.com/article/idUSTRE6133IB20100204
The business cycle rolls on.
* * * * * J B K * * * * *
San Francisco
Geithner: Banks must pay fully for bailout | Reuters
WASHINGTON (Reuters) - The Obama administration is prepared to impose fees on financial firms for as long as necessary to ensure that every cent spent on bailing out banks is repaid, U.S. Treasury Secretary Timothy Geithner said on Tuesday.
Barack Obama
A proposed Financial Crisis Responsibility fee that is projected to raise $90 billion over 10 years could be extended if the cost of the bailout exceeds that amount, Geithner said in testimony before the Senate Finance Committee.
"The fee can and will be extended until every penny of taxpayer assistance to the financial system has been repaid and the cost of the rescue to taxpayers is zero," Geithner said.
http://www.reuters.com/article/idUSTRE6113IB20100202
* * * * * J B K * * * * *
San Francisco
James B. Klein
Paterson Financial Services
WEBSITE: paterson.com
WEBLOG: paterson-financial-services.blogspot.com
NEWS WEBLOG: paterson-financial-services-news.blogspot.com
Saturday, January 23, 2010
Business Cycle Indicators
Leading Economic Indicators jumped 1.0% in the past month, with strength coming from 8 of the ten measures.

Only the average workweek of production workers and manufacturers’ new orders for consumer goods and materials* held steady in December.
A further confirmation of the power behind the Fed's increase in the monetary base, the increase in LEI foreshadows changes in aggregate economic activity.
Coincident Economic Indicators also increased in December and it has gained in five of the last six months. Industrial production made a large positive contribution to the index, more than offsetting the decline in employment in December. Between June and December, the index has grown by 0.6 percent (1.2 percent annual rate).
Observers will note that employment continues to lag more than usual, in both LEI and CEI numbers.
The Lagging Economic Indicators (LAG) have started to bottom, but we are still a long way from a full recovery.
The only positive contributor to the index this month was change in labor cost per unit of output*. The negative contributors – beginning with the largest negative contributor – were commercial and industrial loans outstanding*, average duration of unemployment (inverted), and ratio of consumer installment credit to personal income*. The ratio of manufacturing and trade inventories to sales*, change in CPI for services and average prime rate charged by banks* held steady in December. Based on revised data, the lagging economic index decreased 0.5 percent in November and decreased 0.2 percent in October.
The most important measure here are
- C&I loans
- Consumer installment credit
- Prime rate.
TACTICS
Tactics remain the same. Focus on money market arbitrage, and look for quality lending opportunities.
Continue to shorten the maturity of assets.
Look for distressed assets and fund them with short liabilities until Fed tightening begins.
STRATEGY
The economy is in the early stages of the business cycle, and opportunities to purchase distressed assets will drive profits.
Inflation is beginning around the world, as the unprecedented monetary stimulus of the past year takes firmer hold.
As profitable companies emerge from the wreckage of the recent economic disaster, lending opportunities will increase. Take advantage of this opportunity to expand the roster of the institution's clients.
Thursday, January 14, 2010
Asset-Backed Debt Revival in Europe Led by Ford, BMW (Update1) - Bloomberg.com
Here is evidence that the market for asset-backed debt has finally revived.
--------------------------------------------------------------------------
Asset-Backed Debt Revival in Europe Led by Ford, BMW (Update1)
By Esteban Duarte and Jody Shenn
Jan. 14 (Bloomberg) -- Europe's asset-backed bond market, dormant for a year, is coming back to life as Bayerische Motoren Werke AG and Ford Motor Co. sell more than 1 billion euros ($1.45 billion) of debt backed by automobile loans and leases.
BMW, the world's biggest luxury car maker, is selling 742 million euros of bonds backed by German auto leases, said a banker with direct knowledge of the deal. Dearborn, Michigan- based Ford sold 300 million euros of debt tied to car loans on Jan. 8.
The revival in debt backed by consumer and business payments in the auto industry shows improving investor sentiment as Europe emerges from the recession. Yields on company bonds averaged 4.13 percent yesterday in New York, down from 4.37 percent at the start of the year, according to the Bank of America Merrill Lynch Global Broad Market Corporate Index.
"If BMW is successful, it would be a really good indicator for other issuers now monitoring the market," said Markus Ernst, a credit analyst at UniCredit SpA in Munich. Borrowers testing the waters is "definitely a good sign as it underlines that the market is not drying up," he said.
http://www.bloomberg.com/apps/news?pid=20601087&sid=a2imcii4gez8&pos=4
* * * * * J B K * * * * *
San Francisco
James B. Klein
www.paterson.com
paterson-financial-services.blogspot.com
Tuesday, January 12, 2010
Money Supply Fails to Grow
Here are the latest figures for M1, M2, and MZM.
In each case, the numbers suggest banks aren't making new loans. At this stage in the business cycle, this is predictable.
The question now is when will banks find borrowers with the credentials to justify lending. Paterson believes that process has already begun, and that loans will start to grow in the QII of 2010.
First, the M1 numbers.
This is the raw data, showing growth.

Next, the percentage change since last year. Growth is there, but not enough to keep the economy fueled.

Here are the M2 numbers.
First the total.

Next, percentage change from last year.

Finally the MZM numbers.
Here's the raw data. Again, there's growth, but not enough to fuel the economy.

Next, the percentage change since last year. Banks are not lending.

Summary
Without loans, businesses rely on earnings to fuel future growth. The economy is now at a point when earnings will be insufficient to finance future expansion.
Banks will now begin to find lending opportunities for those firms with credit worthy balance sheets and projects. Lending will begin to increase, and when the year is out, the money supply will be growing again.
Saturday, January 02, 2010
2008 - Disaster in the bond market
A long bond purchased one year ago for $1,000 would be worth $715 today, a decline in value of 28.5%.
Here are the figures from the Wall Street Journal.
On December 31, 2008 the value of the current long bond was 137:05, yielding 2.6677% (This is the 2038 May 15 4.500)
One year later, the same bond traded at 98:05 and yielded 4.6169%
Link: US Treasury Quotes
This is only the beginning of the disaster in bond prices unless the Fed can find a way to decrease the monetary base.
MONETARY BASE

In the same time period, the stock market increased 16% from 6000 to 7100 as Fed stimulus took hold.
NYSE COMPOSITE

During the same time period, commodity prices have soared in the past 18 months after collapsing in 2008.
Notice this is a three year chart.
CRB INDEX

Link: CRB Index
Producer prices have recently began to rise.
PPI

The value of the Euro has recently dropped after a prolonged increase.
EURO

SUMMARY
Increases in the monetary base dominated all other factors in explaining changes in economic activity including the stock market, bond prices, currencies, and commodities.
As banks find credit-worthy customers, consumption, income, production, savings and investment will increase for individuals, businesses and governments.
This time is still a long way off, at least 6 months and maybe as much as 18 months.
TACTICS
Money market arbitrage is still the best tactic for depository institutions. Spreads have narrowed as more market participants bid down yields on high-quality assets.
Let long term assets continue to roll off, and be very careful replacing them. No matter what the Fed does, there will be pressure on the long end of the curve.
Lending is still a difficult proposition with credit quality dominating decision making.
STRATEGY
The institution has weathered the most destructive and dangerous storm since the great Depression of 1929-33.
It is now time to re-asses risk taking. The businesses and borrowers that survived this period will thrive in the years to come.
Identify those businesses and activities in your market and begin to work with these borrowers.
Here are the figures from the Wall Street Journal.
On December 31, 2008 the value of the current long bond was 137:05, yielding 2.6677% (This is the 2038 May 15 4.500)
One year later, the same bond traded at 98:05 and yielded 4.6169%
Link: US Treasury Quotes
This is only the beginning of the disaster in bond prices unless the Fed can find a way to decrease the monetary base.
MONETARY BASE

In the same time period, the stock market increased 16% from 6000 to 7100 as Fed stimulus took hold.
NYSE COMPOSITE

During the same time period, commodity prices have soared in the past 18 months after collapsing in 2008.
Notice this is a three year chart.
CRB INDEX

Link: CRB Index
Producer prices have recently began to rise.
PPI
The value of the Euro has recently dropped after a prolonged increase.
EURO

SUMMARY
Increases in the monetary base dominated all other factors in explaining changes in economic activity including the stock market, bond prices, currencies, and commodities.
As banks find credit-worthy customers, consumption, income, production, savings and investment will increase for individuals, businesses and governments.
This time is still a long way off, at least 6 months and maybe as much as 18 months.
TACTICS
Money market arbitrage is still the best tactic for depository institutions. Spreads have narrowed as more market participants bid down yields on high-quality assets.
Let long term assets continue to roll off, and be very careful replacing them. No matter what the Fed does, there will be pressure on the long end of the curve.
Lending is still a difficult proposition with credit quality dominating decision making.
STRATEGY
The institution has weathered the most destructive and dangerous storm since the great Depression of 1929-33.
It is now time to re-asses risk taking. The businesses and borrowers that survived this period will thrive in the years to come.
Identify those businesses and activities in your market and begin to work with these borrowers.
Tuesday, December 15, 2009
Money Supply Explosion Continues
When the story of this financial disaster is written, the lead item will be the massive expansion of the Monetary Base.
Here are the most recent numbers (in Billions)
2009-10-21 - - - 1949.799
2009-11-04 - - - 2024.393
2009-11-18 - - - 2012.162
2009-12-02 - - - 2093.677
Notice that the most recent number is $80 billion of new money in the system - in two weeks. It used to take a whole year to add that much in reserves.
These are huge numbers and ensure expansion and inflation unless something is done.
Here's the graph. (Click on the graph for a larger version)

This money is now sitting in bank vaults as excess reserves, waiting for bankers to decide who is credit worthy.
As loans pick up, the Fed will begin to withdraw this money from the system, but that time is a long way off.
Here are the most recent numbers (in Billions)
2009-10-21 - - - 1949.799
2009-11-04 - - - 2024.393
2009-11-18 - - - 2012.162
2009-12-02 - - - 2093.677
Notice that the most recent number is $80 billion of new money in the system - in two weeks. It used to take a whole year to add that much in reserves.
These are huge numbers and ensure expansion and inflation unless something is done.
Here's the graph. (Click on the graph for a larger version)
This money is now sitting in bank vaults as excess reserves, waiting for bankers to decide who is credit worthy.
As loans pick up, the Fed will begin to withdraw this money from the system, but that time is a long way off.
Cyclical Indicators
The Yield Spread continues to predict substantial growth in GDP in the years to come, provided the Fed manages the reduction in the monetary base smoothly.
The longer the yield spread remains above 300 basis points, the stronger will be the coming expansion.
Here is the recent chart.
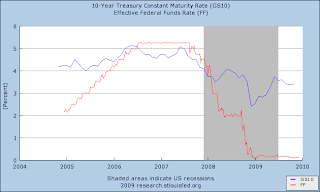
History suggests the yield spread will stay low for another year or more.
In the chart below we see that the yield spread must remain above 300 basis points for long periods to ensure economic growth.

Other Leading Indicators
The Conference Board's Index of Leading Indicators has been positive since March of 2009.
Coincident Indicators are making a bottom and will be turning positive in the next few months as Fed stimulus takes hold.

See Conference Board
The longer the yield spread remains above 300 basis points, the stronger will be the coming expansion.
Here is the recent chart.
History suggests the yield spread will stay low for another year or more.
In the chart below we see that the yield spread must remain above 300 basis points for long periods to ensure economic growth.
Other Leading Indicators
The Conference Board's Index of Leading Indicators has been positive since March of 2009.
Coincident Indicators are making a bottom and will be turning positive in the next few months as Fed stimulus takes hold.

See Conference Board
Bank Lending
Bank lending continues to contract, as banks deny credit to all but the safest borrowers.
Commercial and Industrial Loans - still falling
Consumer Loans - - - - - - - - - still falling
Real Estate Loans - - - - - - - - still falling
At this stage in the business cycle, we expect to see real estate loans turn positive first.
Commercial and Industrial Loans will turn positive in the next 6 months, along with Consumer Loans.
Here is the data.
Click on each graph for a larger view.
First, Commercial and Industrial Loans

Commercial and Industrial Loans in percent.

Next, Real Estate Loans
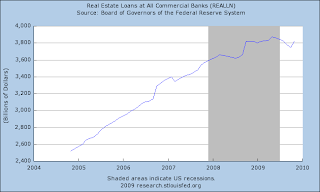
Real Estate Loans - in percent

Consumer Loans

Consumer Loans - in percent

Commercial and Industrial Loans - still falling
Consumer Loans - - - - - - - - - still falling
Real Estate Loans - - - - - - - - still falling
At this stage in the business cycle, we expect to see real estate loans turn positive first.
Commercial and Industrial Loans will turn positive in the next 6 months, along with Consumer Loans.
Here is the data.
Click on each graph for a larger view.
First, Commercial and Industrial Loans

Commercial and Industrial Loans in percent.

Next, Real Estate Loans
Real Estate Loans - in percent
Consumer Loans

Consumer Loans - in percent
Friday, October 09, 2009
Bonds supported by the Fed
The massive purchases of government and agency paper by the Federal Reserve have driven long bond yields below 4%.
Until the Fed stops buying, don't short the long bond.
Until the Fed stops buying, don't short the long bond.
Saturday, July 18, 2009
Monetary Base Dominates Bond Prices
Since the bottom in stock prices, and the top in bonds, the monetary base has dominated all other exogenous variables on the movements of stock and bond prices.
As the base increases, the stock market advances and the bond market declines. Markets follow Fed action precisely.
Thursday's announcement of a major increase in the base has caused a sell-off in bonds and an increase in stocks, gold, and commodities.
As the base increases, the stock market advances and the bond market declines. Markets follow Fed action precisely.
Thursday's announcement of a major increase in the base has caused a sell-off in bonds and an increase in stocks, gold, and commodities.
Saturday, June 06, 2009
Leading Indicators Jump
Leading economic indicators rose sharply in April, the first increase in seven months.
Strengths among its components exceeded the weaknesses for the first time in one and a half years.
Strengthening were the following.
Stock prices,
Interest rate spread,
Consumer expectations,
Initial unemployment claims,
Average workweek, and
Supplier deliveries.
Negative contributions came from these.
Real money supply and
Building permits.
When the real money supply starts to grow, this expansion will be unstoppable.
Look for continued weakness in long bond prices and the dollar.
Thursday, June 04, 2009
Economists in Denial?
Yesterday I went to lunch with a group of economists to discuss the recent disaster in the credit markets.
Here are the main concerns we discussed.
1. The effect of the Fed's purchase of more that $1 trillion of securities and the inevitable inflation arising from the injection of all that high-powered money.
2. The possible inflation coming unless the Fed can sell those securities promptly and reduce the monetary base.
3. The inability of the Fed to begin to sell the hundreds of billions of dollars while unemployment surges.
4. The effects on the falling value of the dollar for government borrowing. No one will want to own dollar denominated assets in this environment.
5. The effects on long maturity interest rates of Treasury borrowing, Fed selling, prudent risk managers not buying, and the dollar dropping.
In summary, most agreed that the situation is far from normal and will not return to normality until the economy recovers and the Fed can pull all this high-powered money out of the system.
That is a long way off.
Yet, three surprising opinions emerged.
1. The cause of inflation. Someone repeated the old confusion about inflation being caused by too much growth rather than too much money. It is astonishing to me that this debate has any credibility at the senior levels of macro analysis.
2. The effects of inflation on the bond and dollar markets. There was little concern over the disaster the US economy is facing and and underestimation of the time it will take to solve this problem.
3. The failure to place the blame for this disaster where it belongs: on Congress, Fannie and Freddie, the SEC, Greenspan's Tsunami in the Fed Funds market beginning in 2004, and unregulated Credit Default Swaps. This is most troubling for future disasters.
TACTICS FOR PORTFOLIO RISK MANAGERS
Brace yourself for higher long rates, a falling dollar, and continued high unemployment.
Extend the maturity of your liabilities as much as you can. The cost of borrowing farther out the curve - as much as 450 basis points - will deter many portfolio risk managers, but those who do will be favored when the yield curve flattens and rises.
It's time to tell senior management and the board that we're in for heavy weather.
Subscribe to:
Posts (Atom)